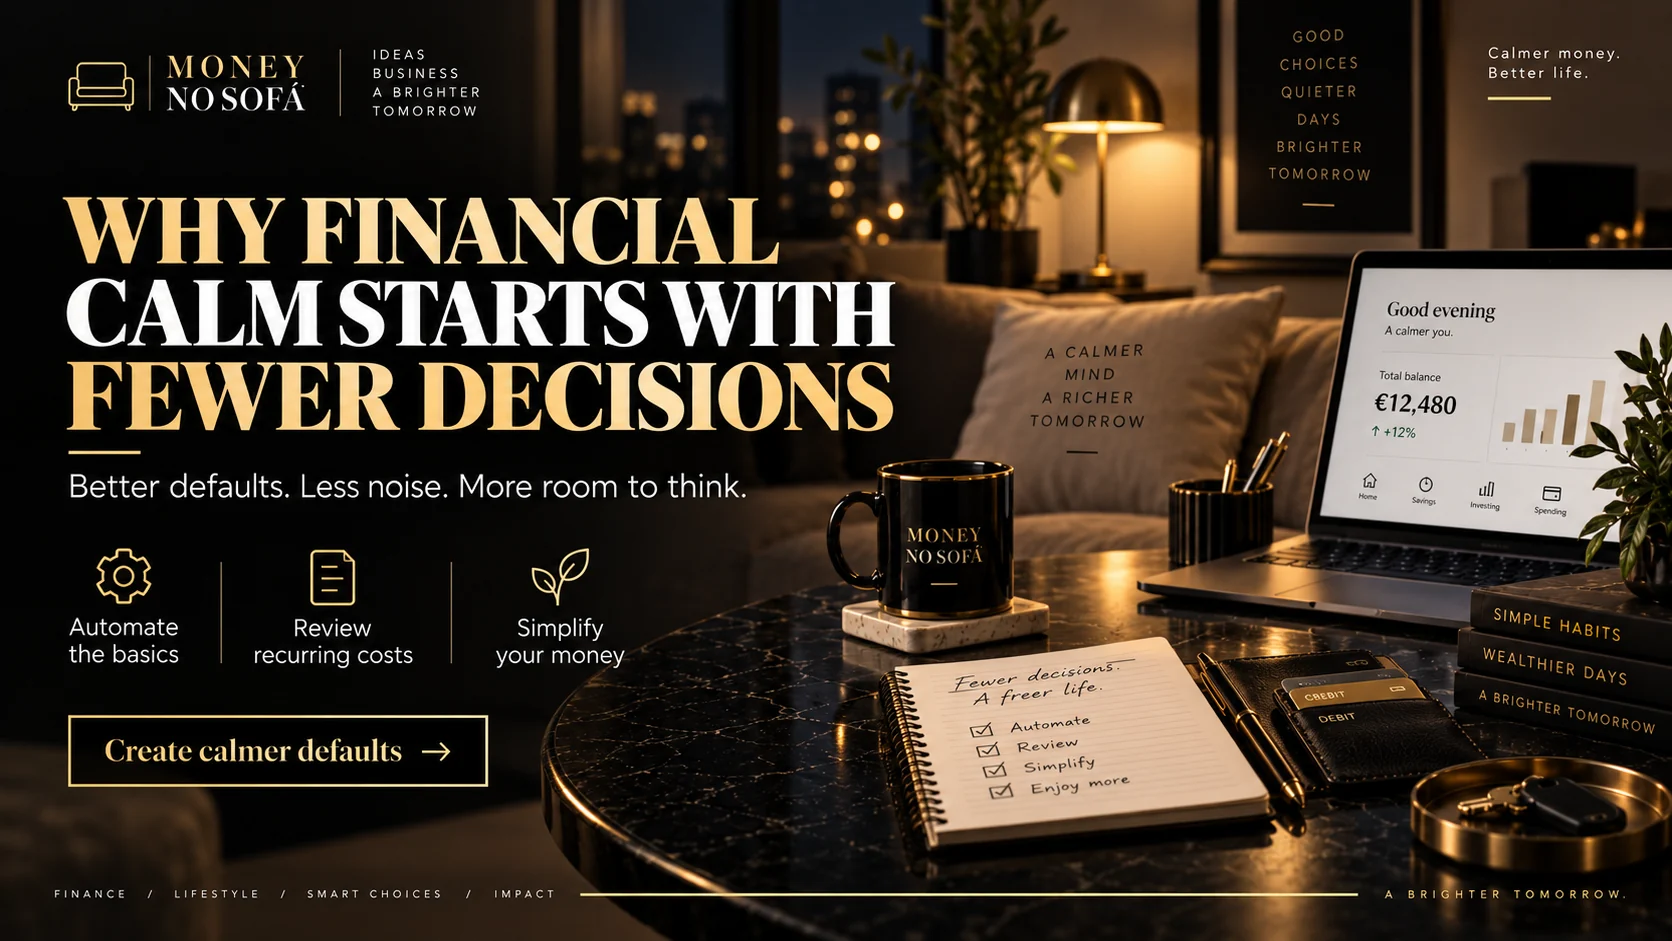
Financial calm is not only about earning more. It often comes from reducing the number of money decisions that demand your attention every week.
Financial calm is often treated like a personality trait. Some people are “good with money,” others are anxious, impulsive or disorganized.
A more useful view is that calm is partly a system design problem. The more money decisions you force yourself to make every day, the more opportunities there are for fatigue, avoidance and inconsistency.
Decision fatigue is expensive
Should I save this week? Which account should I use? Can I spend this amount? Did that bill already get paid? Should I cancel that subscription?
None of these questions is difficult by itself. Together, they create background mental load.
When people are tired, busy or stressed, the easiest option tends to win. That can mean postponing a transfer, ignoring a statement or spending without checking the plan.
Defaults can create calm
A simple money system can answer routine questions automatically.
- Fixed bills come from one account.
- Savings move automatically after payday.
- Subscriptions are reviewed on one fixed date.
- Discretionary spending has a clear monthly amount.
- Large purchases trigger a waiting rule.
None of these rules is sophisticated. Their value comes from removing repeated negotiation with yourself.
Automation should support awareness
There is a danger in automating everything. If money moves without ever being reviewed, a calm system can become an invisible system.
The right balance is automatic execution plus periodic attention.
For example, automate the savings transfer, but review the amount quarterly. Automate bills, but scan the account once a week. Keep subscriptions automatic, but run a monthly audit.
We explore the positive side of this in How to Use Smart Tools and Better Habits to Save More Money.
Clarity reduces emotional noise
Anxiety often grows when money feels vague. A bill might be coming. A balance might be too low. A purchase might be okay.
Clear numbers reduce that uncertainty. Knowing your baseline monthly expenses, current buffer and available discretionary amount turns many emotional questions into simple operational ones.
You do not need a perfect spreadsheet. You need a few numbers you trust.
Protect decision energy for the big choices
Once routine money is structured, you have more attention for decisions with real consequences: changing jobs, taking on debt, buying a home, choosing insurance, investing or supporting family.
That is where thinking deserves time.
Financial calm is not the absence of financial decisions. It is the absence of unnecessary repeated decisions.
Write down three money decisions you make repeatedly. Turn one into a default this week: automate it, schedule it or create a simple rule so you no longer have to renegotiate it every time.
Money no Sofá — Money for real life.
The headline is only the start.
Ask Nova what this story could change in your budget, savings, debt, investments or next purchase.