Bitcoin did more than create a new asset. It challenged who controls supply, when value can move and what financial ownership demands from ordinary people.
Bitcoin did not need to replace every bank, defeat every government or become the world’s only currency to change money forever. It only needed to prove that a scarce digital asset could move between people without a central institution controlling the ledger.
That sounds technical. Its consequences are not.
For generations, most people treated the rules of money as laws of nature. Banks held balances. Governments issued currencies. Payments crossed borders slowly. Financial institutions decided who could participate, how long settlement would take and what information had to be provided. Individuals could own cash, but large-scale economic life depended on permissioned systems.
Bitcoin introduced a competing set of rules. Its network is open. Its monetary supply follows a published schedule. Ownership can be represented by cryptographic keys. Transactions can settle without a bank updating its private database. The system operates continuously, across borders, with no single company able to switch it off.
This does not automatically make Bitcoin good, safe or suitable for every person. It does mean that the old rules are no longer the only possible rules.
The old monetary system was built on trusted gatekeepers
Traditional money works because societies accept a chain of trusted institutions. A central bank manages the base currency. Commercial banks maintain accounts. Payment processors transmit instructions. Card networks authorize purchases. Regulators define obligations. Courts resolve disputes. Governments collect taxes and enforce contracts.
This architecture provides real benefits. It allows credit, fraud controls, consumer protections, reversals, identity verification and monetary policy. It also concentrates power. A payment can be blocked. An account can be frozen. A transfer can be delayed. Access can depend on geography, documentation, business hours, political stability and the policies of intermediaries.
Before Bitcoin, the normal response was not to question the structure. It was to choose a better bank, a faster card or a cheaper transfer service. The system could be improved, but its basic design remained the same: a trusted third party recorded ownership and approved movement.
Bitcoin asked a more radical question: what if the ledger itself could be maintained by a distributed network, with rules enforced by software and cryptography rather than by one central operator?
Rule one: money needs a central issuer
National currencies have identifiable issuers. A central bank can expand or contract the monetary base, influence interest rates and respond to financial crises. The flexibility is intentional. It gives policymakers tools to support liquidity, employment, price stability and the banking system.
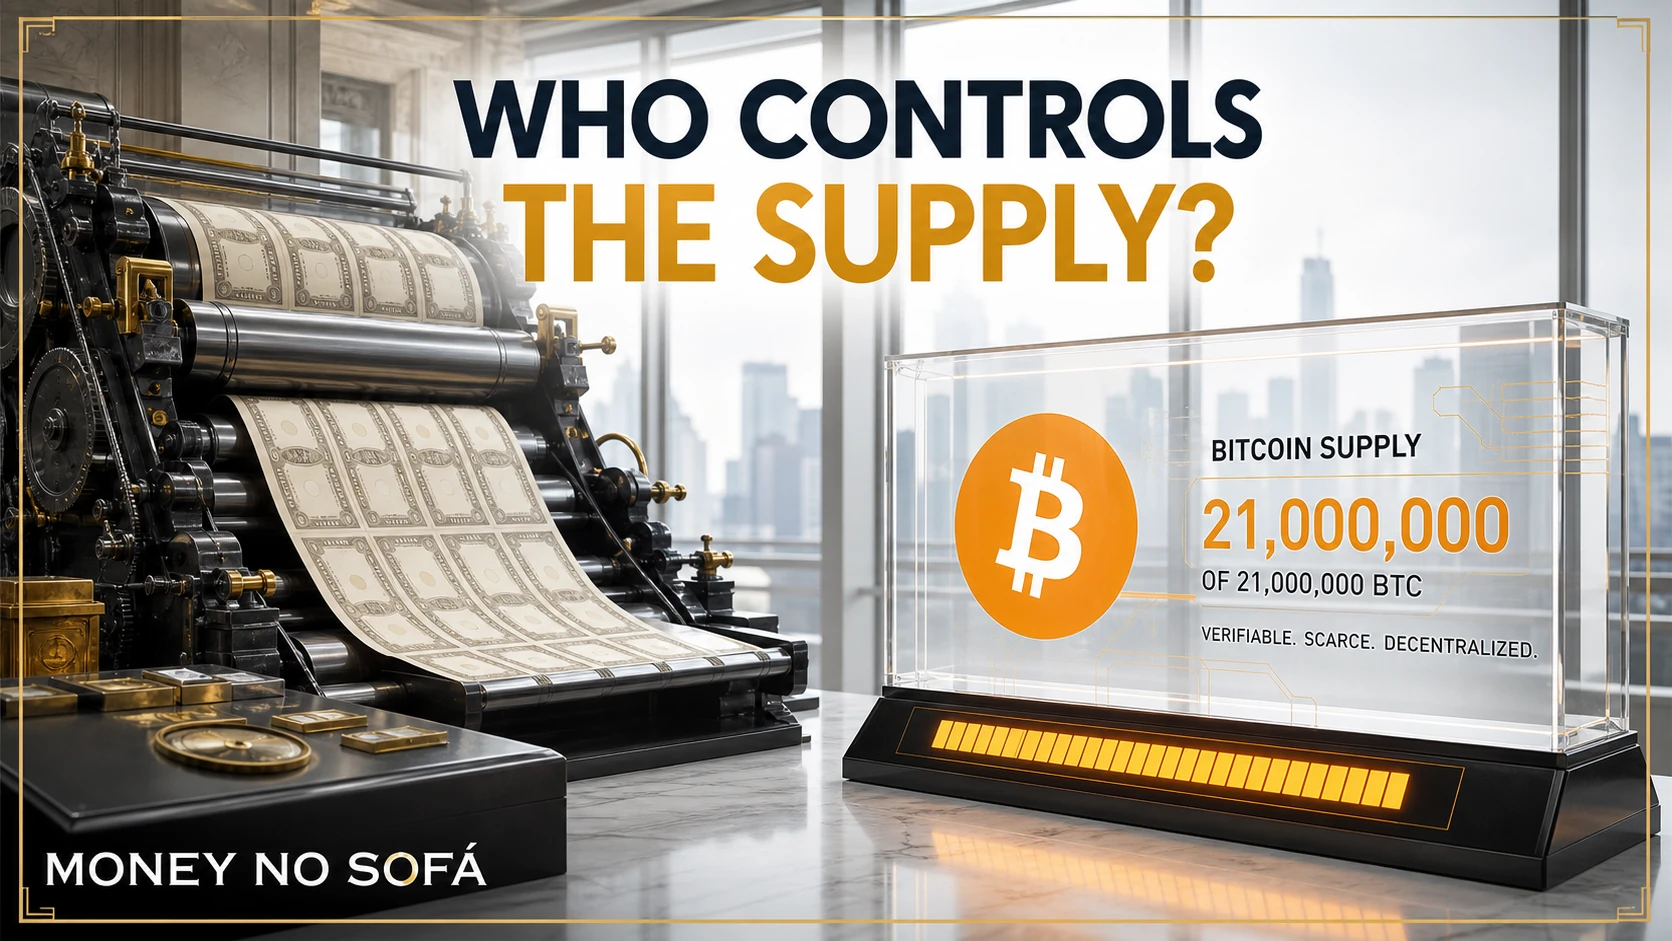
Bitcoin rejected that model. New units are issued according to rules encoded in the protocol. The reward paid to miners declines periodically, and the total supply approaches a fixed maximum of 21 million bitcoin. Changing that limit would require broad coordination among participants who have little incentive to dilute their own holdings.
The important innovation is not merely scarcity. Many things are scarce. The innovation is a digital scarcity that can be independently verified. A participant does not need to trust a company’s promise that supply is limited. Anyone can inspect the rules and validate the ledger with software.
This changed the monetary conversation. People began asking questions that had rarely entered ordinary household finance: Who controls issuance? Can the rules change? How transparent is supply? What is the difference between discretionary and programmatic monetary policy? What happens when trust shifts from institutions to code?
Bitcoin did not prove that fixed supply is always superior. Economists disagree strongly about the benefits and risks of inflexible money. But it proved that a global digital asset can exist without a central issuer. That possibility cannot be uninvented.
Rule two: digital value can be copied
Digital information is normally easy to duplicate. A photo, song or document can be copied perfectly. Money cannot work that way. If one unit can be spent twice, the system collapses.
Traditional payment systems solve this through central databases. The bank checks whether the account has sufficient funds, updates balances and prevents the same money from being used again.
Bitcoin’s breakthrough was a practical method for reaching agreement about transaction history without one central database owner. Transactions are grouped into blocks. Miners compete to add valid blocks through proof of work. Nodes independently verify that the protocol’s rules have been followed. The chain with the greatest accumulated work serves as the accepted history.
The result is not magical perfection. Bitcoin can experience congestion, fees can rise, users can make mistakes and software can contain vulnerabilities. Yet the network demonstrated that digital scarcity and decentralized settlement could work at global scale for an extended period.
Once that happened, money was no longer the only category affected. The same basic insight inspired thousands of experiments involving tokens, smart contracts, digital ownership and decentralized applications. Many failed. Some were fraudulent. Others created useful infrastructure. The broader crypto industry became chaotic precisely because Bitcoin opened a door that had previously appeared locked.
Rule three: financial access follows borders and schedules
Banking is deeply connected to jurisdiction. Accounts are opened under national laws. Transfers pass through correspondent institutions. International settlement can involve multiple intermediaries, currency conversions and compliance checks. Even modern digital banking often rests on systems that close, batch or delay transactions.
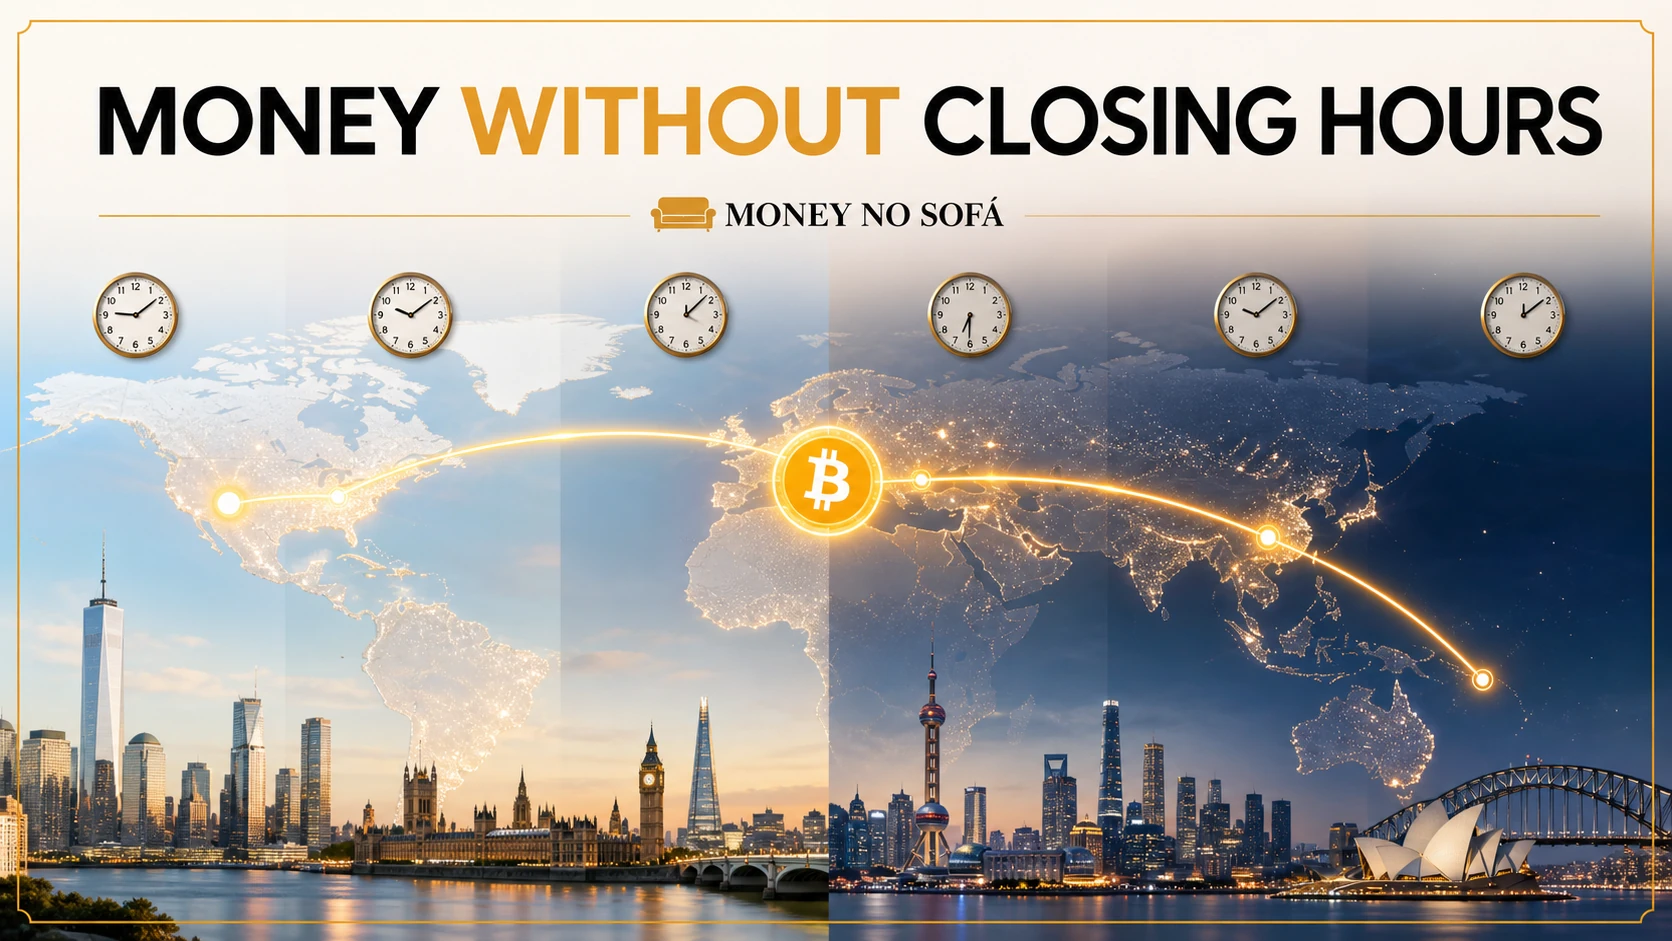
Bitcoin operates differently. The network does not recognize weekends, holidays or national borders. A valid transaction can be broadcast at any time. The protocol does not ask whether the sender lives in São Paulo, New York, Lagos or Tokyo.
This openness is one of Bitcoin’s strongest promises and one of its hardest challenges. A borderless network can serve legitimate users excluded from efficient finance. It can also be used to move value in ways that frustrate law enforcement, sanctions and capital controls. The same neutrality that protects an ordinary user from arbitrary exclusion can protect a criminal from traditional surveillance.
That tension will not disappear through slogans. Bitcoin forces societies to debate how much financial freedom individuals should have, how much visibility governments require and where responsibility should sit when a network has no central operator.
The old system made these decisions inside institutions. Bitcoin moved them into public conflict.
Rule four: custody belongs to institutions
Most people do not directly hold the assets represented in their financial accounts. Banks safeguard deposits. Brokers custody securities. Payment companies store credentials. This arrangement is convenient because institutions handle security, recovery and recordkeeping.
Bitcoin allows a different model. A person who controls the private keys can control the bitcoin associated with those keys. No bank manager needs to approve the transfer.
This is often summarized as financial sovereignty. The phrase sounds empowering, but sovereignty includes responsibility. Lose the keys and there may be no help desk. Reveal a recovery phrase and the funds may be stolen. Send bitcoin to the wrong address and reversal may be impossible. Store everything with an exchange and the user has recreated the dependency Bitcoin was designed to avoid.
Self-custody therefore changes the consumer relationship with risk. Traditional finance places significant operational responsibility on institutions. Bitcoin can return that responsibility to the individual. Some people value that control. Others reasonably prefer regulated custody, insurance and customer support.
The future is unlikely to be purely self-custodial or purely institutional. More likely, different users will choose different levels of control. Families may keep small amounts in personal wallets and larger amounts with qualified custodians. Businesses may use multi-signature arrangements. Institutions may offer recovery systems without gaining unilateral control.
Bitcoin’s contribution was not to eliminate custody services. It was to make them optional in a way that had never been possible for a native digital bearer asset.
Rule five: settlement should be invisible to the public
When a card payment is approved, the consumer sees a simple confirmation. Behind it sits a complicated chain of authorization, clearing, settlement, fees, chargeback exposure and counterparty risk. The apparent transfer is often a promise that final settlement will happen later.
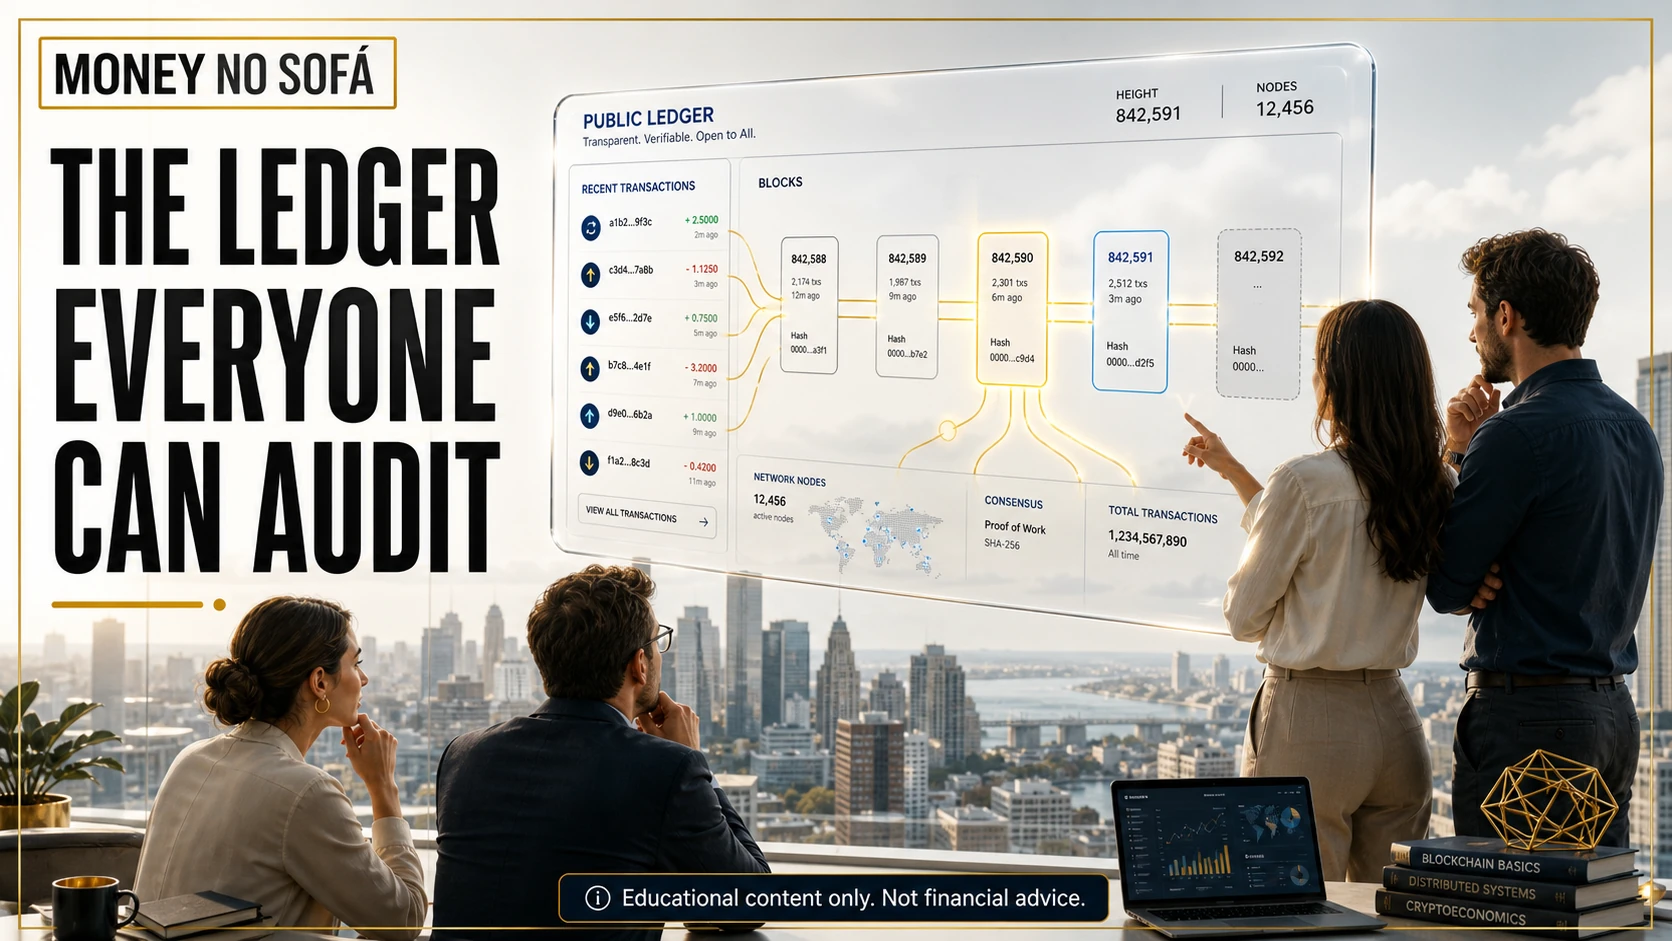
Bitcoin exposes a different model. Transactions appear on a public ledger. Users can independently verify whether funds moved and how many confirmations followed. Settlement is probabilistic at first and becomes increasingly difficult to reverse as additional blocks are added.
Transparency changes behavior. Researchers can analyze flows. Companies can prove that transactions occurred. Criminal investigators can trace patterns. Competitors can observe large movements. Users can verify reserves only when institutions provide the necessary address information and liabilities are also accounted for.
Public transparency is not the same as perfect identity. Bitcoin addresses are pseudonymous, not automatically tied to real names. Once an address is linked to a person or company, however, transaction history can become highly revealing.
This creates another trade-off. The traditional system gives institutions deep private visibility while the public sees little. Bitcoin gives the public deep ledger visibility while identities may remain uncertain. Neither model offers complete privacy. They distribute visibility differently.
Bitcoin changed banks even without replacing them
The most dramatic Bitcoin narratives imagine a total victory: banks disappear, governments lose monetary power and a decentralized currency becomes the universal standard.
Reality may be less theatrical and more consequential.
Banks do not need to vanish for Bitcoin to influence them. The existence of an open settlement network creates competitive pressure. Customers may demand faster transfers, clearer fees, continuous service and greater control. Financial institutions may offer Bitcoin custody, trading, collateral services or tokenized products. Central banks may accelerate research into digital currencies and instant-payment systems. Regulators may modernize rules for digital assets.
In other words, Bitcoin can change the system by forcing incumbents to respond.
The internet did not eliminate every newspaper, store or television company. It changed the economics under which they operated. Bitcoin may have a similar effect on finance. It creates an alternative architecture that institutions can compete with, regulate, adopt or integrate.
The old question was whether Bitcoin would replace banks. The better question is how banks behave once customers know that another model is technically possible.
Bitcoin changed governments without becoming a country
Governments rely on monetary systems for taxation, spending, financial supervision and economic management. A borderless asset complicates each of these functions.
Bitcoin can move across jurisdictions through information. It can be memorized through a recovery phrase. It can be held outside a domestic banking system. It can create an alternative store of value during periods of political or monetary instability.
Governments still possess powerful tools. They regulate exchanges, banks, businesses and taxpayers. They control legal tender rules. They enforce reporting requirements. They can restrict mining, advertising or financial access. They can prosecute illegal activity. Bitcoin does not make states powerless.
What it does is raise the cost of absolute financial control. A government may block a company more easily than it can eliminate a decentralized protocol operating across many countries. Enforcement shifts toward access points: exchanges, custodians, merchants, internet infrastructure and identifiable users.
This creates a long-term negotiation between networks and states. The likely outcome is not total defeat for either side. It is an evolving boundary between individual control and public authority.
Bitcoin changed the meaning of ownership
Ownership in modern finance often means having a legally recognized claim recorded by an institution. Bitcoin adds another form: control demonstrated through cryptographic keys.
These forms can overlap, but they are not identical. A thief who steals a private key may control the asset without having a legitimate legal claim. An heir may have a legal claim but no technical access. A custodian may control keys on behalf of customers whose rights depend on contracts and regulation.
This gap between technical control and legal ownership creates difficult questions for inheritance, bankruptcy, divorce, taxation, lending and consumer protection.
It also creates new planning responsibilities. A household holding bitcoin needs more than a price target. It needs a custody policy, recovery process, documentation method and inheritance plan. Without those systems, the asset may become inaccessible precisely when the family needs it.
The headline promise of Bitcoin is individual control. The mature practice of Bitcoin is controlled procedure.
What Bitcoin did not solve
Revolutionary technology is often judged by the problems it promises to solve and excused for the problems it creates. Bitcoin deserves a more disciplined evaluation.
It did not eliminate volatility. A scarce asset can still rise or fall dramatically when demand changes.
It did not eliminate fraud. The protocol may operate as designed while exchanges, promoters and users behave dishonestly.
It did not eliminate inequality. Early buyers, miners and large holders can accumulate substantial influence and wealth.
It did not eliminate dependence on infrastructure. Users still need devices, electricity, communications, software and secure storage.
It did not eliminate regulation. Businesses and individuals remain subject to laws where they operate.
It did not guarantee privacy. Public transaction history can expose behavior when addresses are linked to identities.
It did not make financial judgment unnecessary. A person can lose money through leverage, panic, concentration, scams or simple misunderstanding.
Bitcoin changed the rules of what is technically possible. It did not repeal economics, law or human behavior.
The environmental argument is more complex than either side admits
Bitcoin mining consumes electricity because proof of work requires computational effort. That energy use is not an accidental side effect; it is part of the mechanism that makes altering transaction history expensive.
Critics argue that the social value does not justify the consumption and associated emissions, especially where mining relies on fossil fuels. Supporters argue that miners can use stranded, curtailed or renewable energy, provide flexible demand and monetize resources that would otherwise be wasted.
The honest conclusion depends on location, energy mix, grid conditions, equipment efficiency and the value assigned to the network. A megawatt used in one place may have very different consequences from a megawatt used elsewhere.
Readers should distrust simple claims that Bitcoin is either environmentally harmless or uniquely catastrophic. The relevant questions are measurable: What energy is being used? What alternative demand exists? What emissions result? Does mining support or strain the grid? Who receives the economic benefit?
Bitcoin did not end the environmental debate. It made energy policy part of the monetary debate.
The volatility time bomb
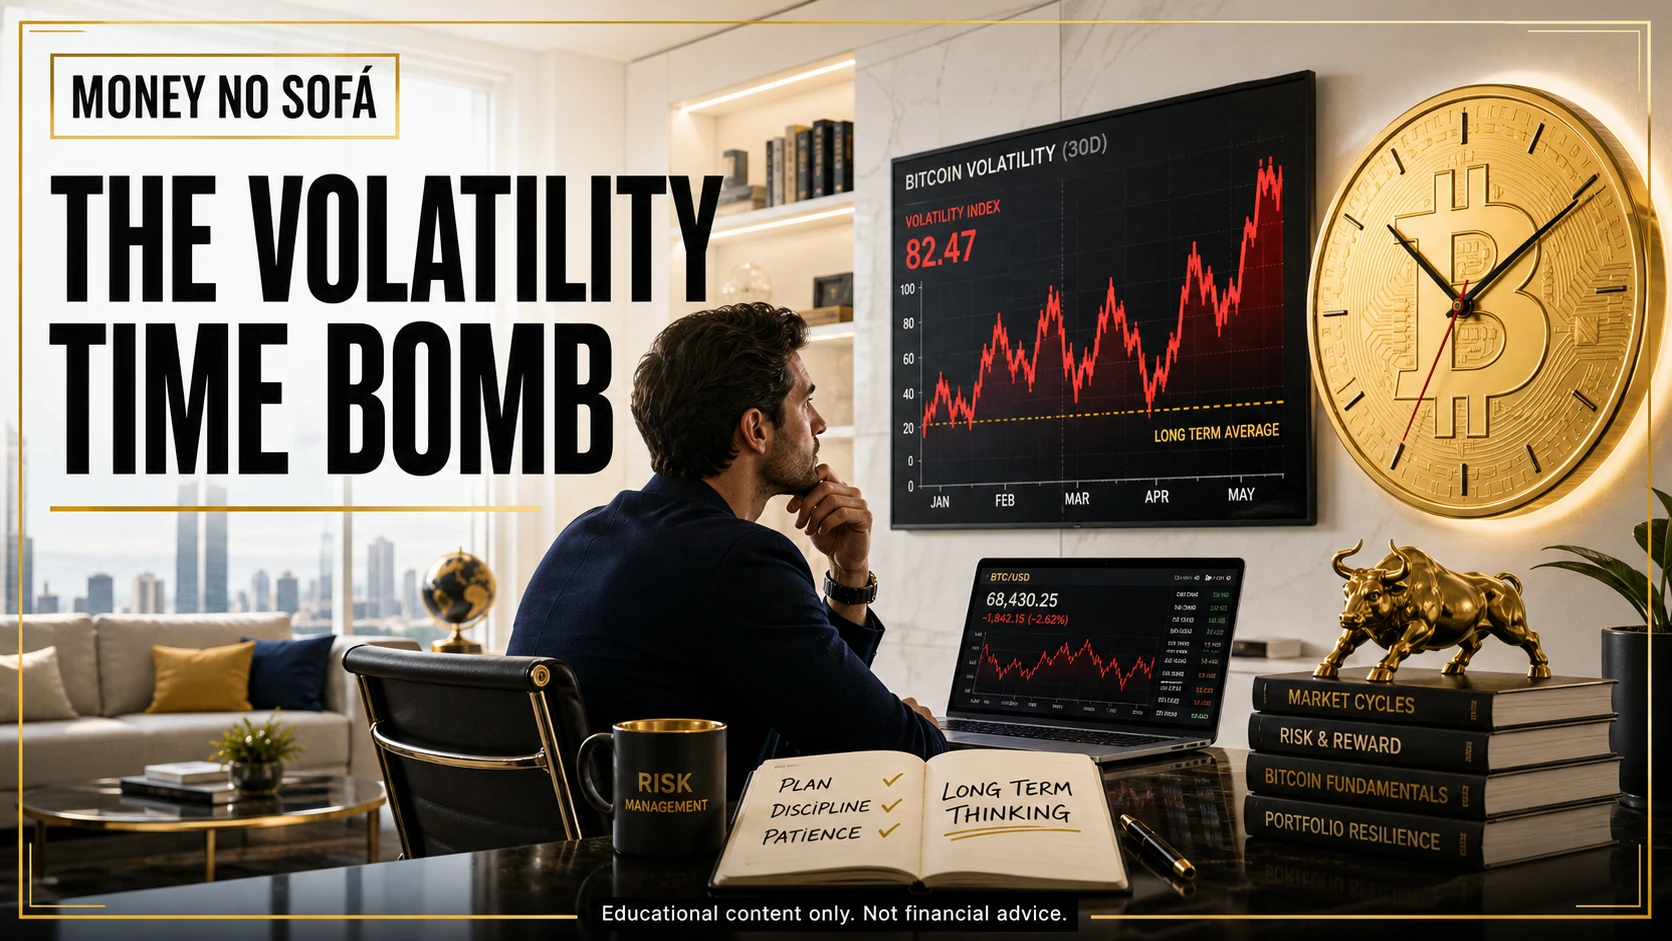
Bitcoin’s price can move quickly because it trades continuously, its supply response is limited and its demand is shaped by sentiment, liquidity, regulation, leverage and macroeconomic conditions.
Volatility attracts attention and speculation. It also limits everyday use. A household cannot responsibly treat a highly volatile asset as emergency savings needed next month. A company may hesitate to price wages or inventory in a unit whose purchasing power can change sharply. A leveraged investor can be liquidated even when the long-term thesis later proves correct.
The danger grows when Bitcoin becomes connected to the broader financial system through loans, derivatives, corporate balance sheets and institutional products. Integration can increase liquidity and legitimacy, but it can also transmit shocks.
This does not mean Bitcoin will cause a financial collapse. It means risk should be evaluated at the connections: leverage, collateral, concentration, custody and maturity mismatch. The asset itself is only one part of the system built around it.
For individual readers, the practical lesson is simple: enthusiasm is not a risk-management plan.
New to digital assets? Start with our crypto beginner safety guide before moving money or connecting a wallet.
A practical framework for ordinary people
Bitcoin discussions often force people into two camps: believers and enemies. That framing is commercially useful and intellectually weak. An ordinary person can study Bitcoin without buying it, own a small amount without treating it as salvation, or reject it after understanding the trade-offs.
1. Separate the network from the price
The network is a technical and economic system. The price is what buyers and sellers agree on at a given moment. A useful network can be overpriced. A falling price does not automatically mean the technology failed. A rising price does not prove every claim made by promoters.
2. Define the role before choosing the amount
Is Bitcoin being considered as education, speculation, long-term diversification, a payment tool or protection against a particular risk? Different purposes require different amounts, time horizons and custody choices.
3. Protect essential money
Rent, food, medication, taxes, debt payments and emergency reserves should not depend on a volatile asset recovering at the right time. Financial resilience comes before asymmetric opportunity.
4. Avoid borrowed conviction
Using debt or leverage to buy Bitcoin converts uncertainty into obligation. The market can wait longer than a borrower can remain solvent.
5. Learn custody before transferring large amounts
Understand exchanges, withdrawal addresses, transaction fees, private keys, recovery phrases, hardware wallets, backups and inheritance. Test with a small amount first.
6. Assume every urgent message is hostile
Scammers exploit greed, fear and confusion. No legitimate support agent needs a recovery phrase. Guaranteed returns are not guarantees. Urgency is a warning signal.
7. Create an exit and review policy
Decide in advance when to rebalance, take profits, reduce exposure or admit that the original thesis changed. A plan made during calm conditions is usually better than a decision made during panic.
Three possible worlds after Bitcoin
Scenario one: Bitcoin becomes digital gold
In this world, Bitcoin is held primarily as a scarce reserve asset. It does not replace everyday currency. Banks, funds, companies and individuals use it as a long-term store of value or portfolio diversifier. Payment layers and custodians make access easier, while governments regulate the surrounding industry.
This scenario changes savings and reserves more than daily shopping.
Scenario two: Bitcoin becomes financial infrastructure
Here, Bitcoin’s base layer serves as a settlement network, while faster systems handle everyday transactions. Financial products, collateral markets and international transfers develop around it. Users may interact with Bitcoin without understanding the underlying protocol, just as internet users rarely understand routing.
This scenario changes how value moves, even if prices are still displayed in national currencies.
Scenario three: Bitcoin remains important but limited
Bitcoin survives as a major alternative asset but faces constraints from volatility, regulation, usability, environmental concerns and competition. It influences policy and technology without becoming dominant.
This scenario still represents a historic change. A decentralized digital asset would have established a permanent place beside traditional financial instruments.
There is also a failure scenario. A severe technical flaw, coordinated loss of confidence, hostile regulation, superior alternatives or a collapse in economic incentives could reduce Bitcoin’s relevance. No serious analysis should pretend that survival is guaranteed.
The real revolution was permission
The most important thing Bitcoin changed may not be money itself. It changed who is allowed to experiment with money.
Before Bitcoin, creating a global monetary network required governments, banks, licenses, capital and institutional agreements. Bitcoin began as software released to the public. Anyone could inspect it, run it, mine it, use it or build around it.
That permissionless quality produced extraordinary innovation and extraordinary waste. It enabled open-source development, new businesses and financial access. It also enabled speculative mania, misleading tokens and industrial-scale fraud.
Permissionless systems increase the range of possible outcomes. They do not guarantee good outcomes.
The challenge for the next generation is to preserve useful openness while improving safety, accountability and usability. That work will involve developers, regulators, institutions and users. No single group controls the answer.
Bitcoin ended certainty, not the world
Bitcoin did not end the world. It ended the certainty that money must work in only one way.
It proved that a decentralized network could maintain a scarce digital asset. It allowed individuals to hold and transfer value through cryptographic keys. It created a global market that never closes. It forced banks, governments and investors to confront a system that does not fit neatly inside traditional categories.
The old rules still dominate most economic life. Salaries, taxes, loans, prices and public spending remain tied to national currencies and regulated institutions. Bitcoin has not replaced that architecture.
But dominance is not the same as exclusivity.
From the moment Bitcoin survived long enough to become economically meaningful, the world gained a second set of monetary possibilities. Future systems may use Bitcoin directly, borrow its ideas or compete against it. Governments may restrict it, institutions may absorb it and markets may repeatedly misprice it. None of that removes the central fact: digital scarcity without a central issuer is now a demonstrated reality.
The old financial world assumed trust had to be concentrated. Bitcoin showed that trust could be redistributed among code, computation, incentives and independent verification.
That may not be the end of money. It may be the beginning of a much larger argument about who gets to control it.
CG81 reader checklist
- Can you explain Bitcoin without mentioning its price?
- Do you understand the difference between an exchange account and self-custody?
- Have you protected emergency savings before taking investment risk?
- Could your family access your assets if something happened to you?
- Do you know what evidence would change your opinion about Bitcoin?
- Are you evaluating the network, the asset and the surrounding industry separately?
- Have you considered legal and tax obligations in your jurisdiction?
Educational notice: This article is general editorial information. It is not financial, investment, legal or tax advice. Bitcoin and other digital assets can be volatile and involve loss, custody, fraud, regulatory and technology risks. Decisions should reflect personal circumstances and, when appropriate, guidance from qualified professionals.
Continue Learning About Bitcoin
For the banking angle, read how Bitcoin challenged the banking imagination. For a simpler foundation, continue with Bitcoin explained in plain language.
For a book-length introduction to Bitcoin’s origins, Satoshi and the ideas behind money, explore The Bitcoin Trilogy — Complete Set.
The headline is only the start.
Ask Nova what this story could change in your budget, savings, debt, investments or next purchase.