16/09/2026
Nubank 3.50% APY: How Much $10,000 Earns in One Year
Nubank’s new U.S. account pays 3.50% APY. Here is how much $1,000, $5,000, $10,000 and $25,000 earn in one year — and the gap…
Practical money guidance for everyday decisions, from budgeting and debt to saving, investing and financial confidence.
Nubank’s new U.S. account pays 3.50% APY. Here is how much $1,000, $5,000, $10,000 and $25,000 earn in one year — and the gap…
At 4.50% APY, $10,000 earns about $450 in one year before taxes if the rate holds. Here is the math for $1,000, $5,000, $10,000…
The Fed raised rates to 3.75%–4.00%. See what that means for credit cards, variable debt, mortgages, savings accounts, CDs and household decisions.
U.S. builder confidence fell to a one-year low in September, while 38% of builders cut prices by an average 6%. On a $500,000 new…
Last updated: September 17, 2026 — 3:01 PM BRT Summary: Brazil’s Supreme Court has still not decided whether to open an investigation involving Justice…
The Cost of Keeping Too Many Money Options Open More options can feel like more control. In money, too many accounts, cards, apps and…
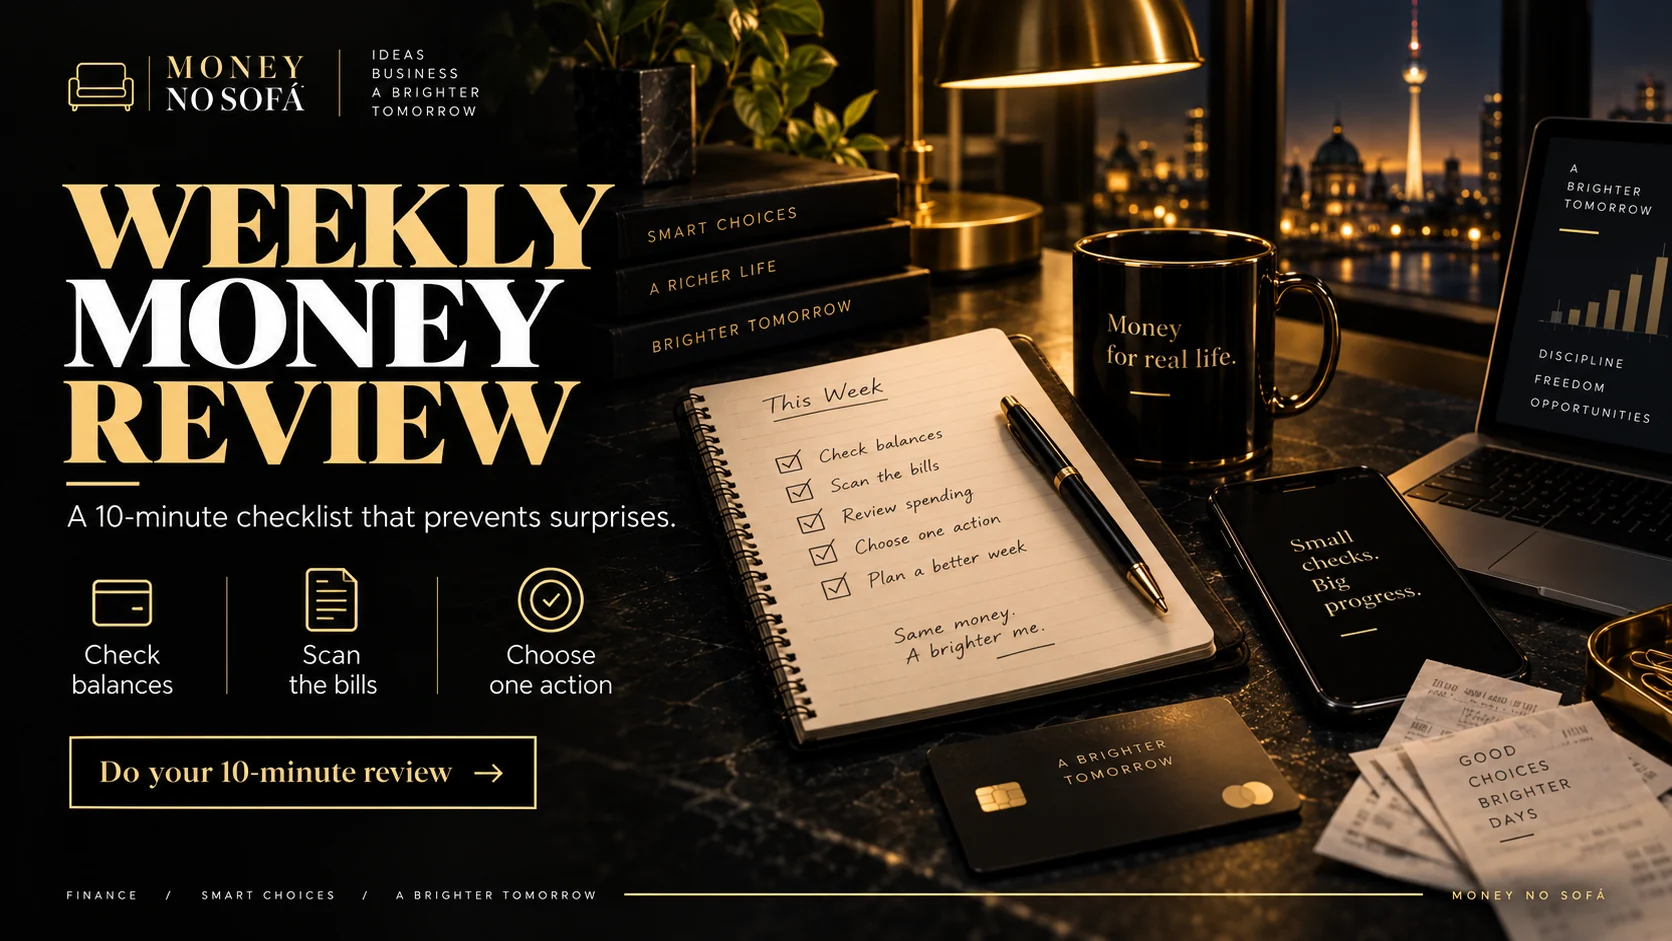
The 10-Minute Money Review That Prevents Surprises You do not need to stare at your money every day. Ten useful minutes once a week…
Motivation changes. A clear financial picture makes the next action easier even on ordinary days when enthusiasm is low.
Spending less for one month can help, but a strong financial system is built to survive ordinary life, irregular bills and imperfect motivation.
Automation can reduce errors, but some financial choices need context. Knowing what not to automate is part of a healthy money system.
Automation works best on predictable financial tasks. The right automations reduce errors without removing judgment from important decisions.
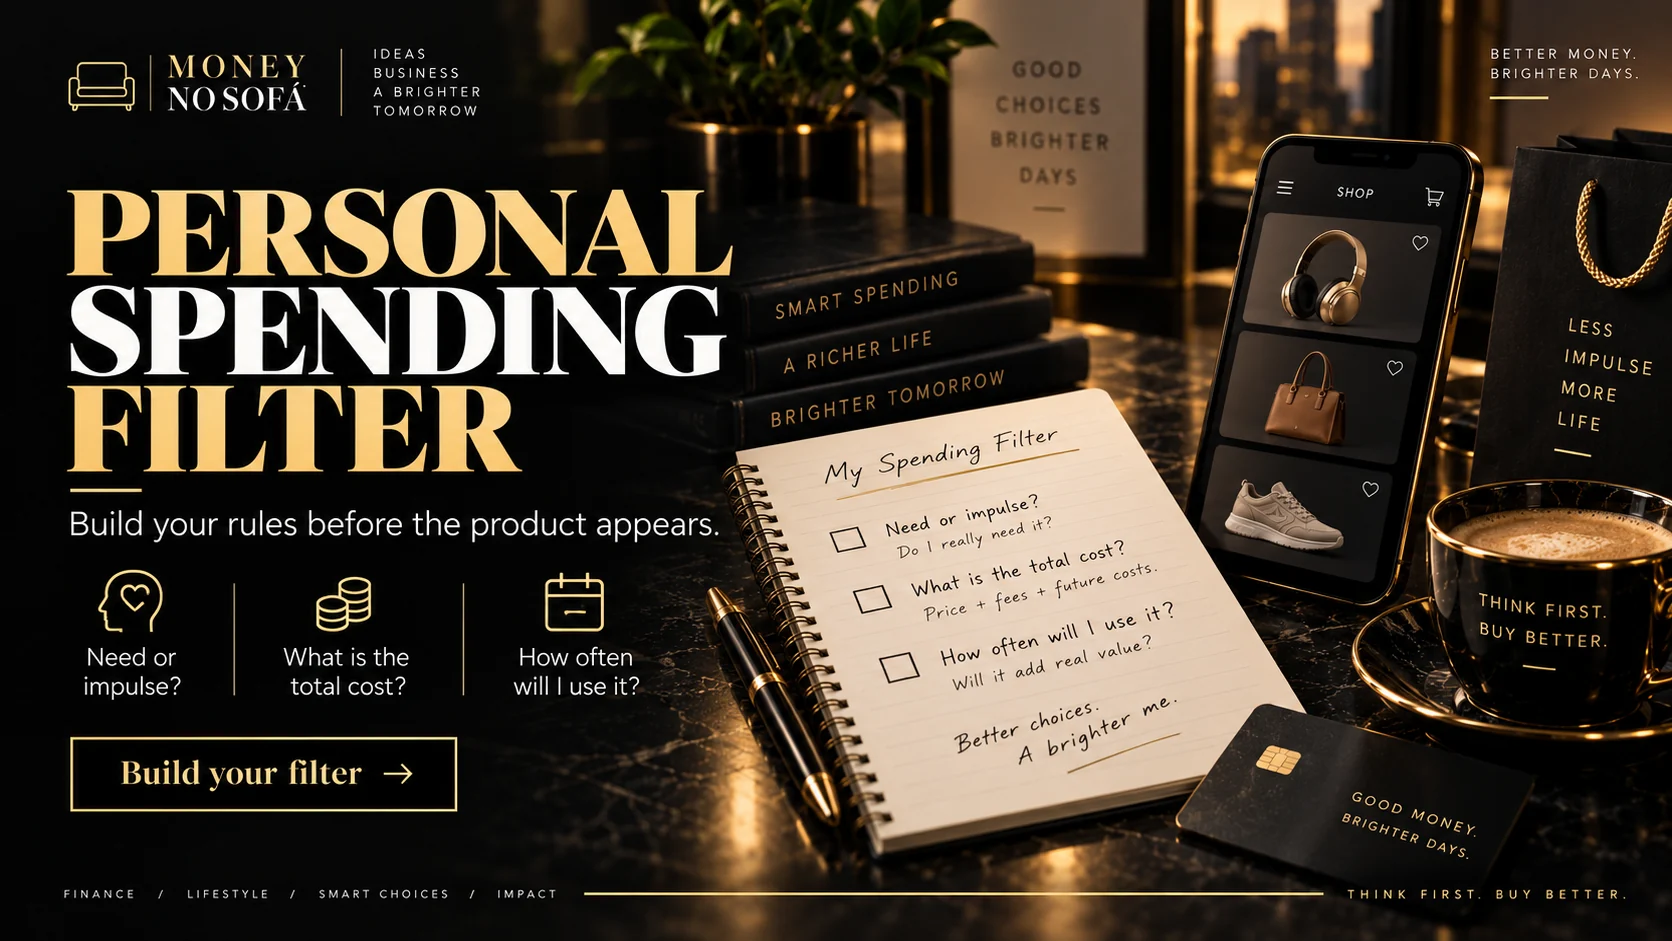
A simple spending filter can make buying decisions faster and cleaner by defining what matters before the product starts persuading you.
A short weekly money review can catch small problems before they become expensive ones. Ten focused minutes are often enough.
Good financial habits are easier when the default behavior already points in the right direction. Systems can reduce the need for constant self-control.
Installments, subscriptions and recurring services can make today easier by committing tomorrow’s income. That trade deserves to stay visible.
Too many financial choices can create stress, delay and weak decisions. Simplifying your options can make money easier to manage.
Financial calm is not only about earning more. It often comes from reducing the number of money decisions that demand your attention every week.
Affordability is more than having enough money today. A better question is whether the purchase still fits after you account for what it displaces.
Modern spending is not only a money problem. It is an attention problem. The easier it is to interrupt you, the easier it is…
Delivery fees, service fees and platform charges can be worth paying. The problem starts when convenience becomes a default rather than a choice.
Auto-renewal turns yesterday’s choice into today’s expense. That is convenient—but it can also keep old decisions alive too long.